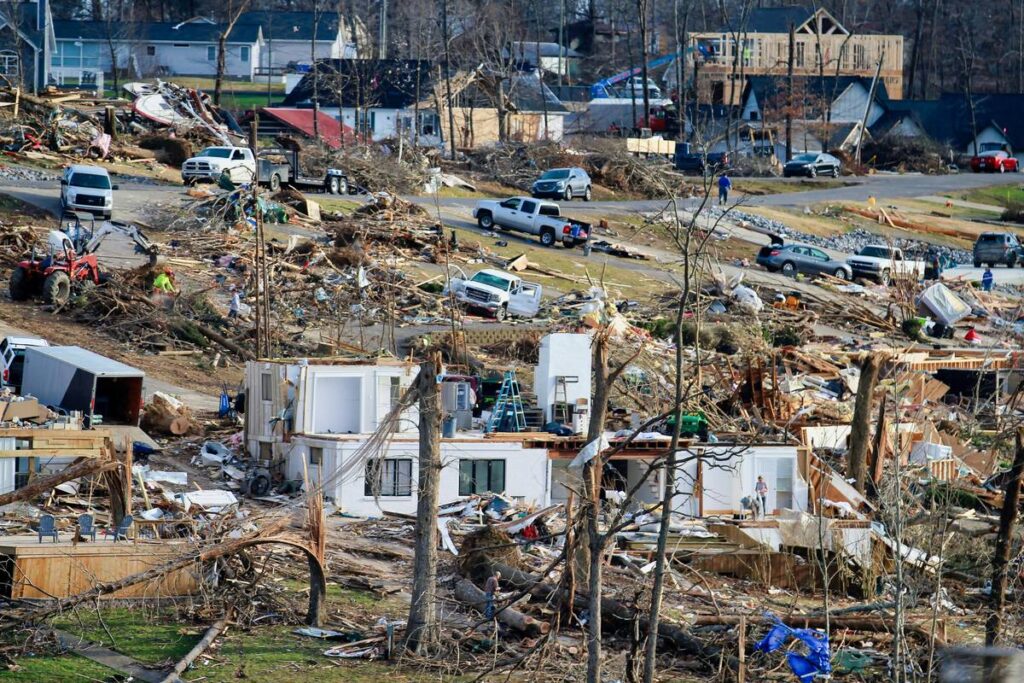
If your dog hides under the couch every time storm clouds roll in, you already know tornadoes don’t just threaten your roof—they can shatter your pet’s safety net. Yet most pet insurance policies treat natural disasters like afterthoughts. I learned this the hard way when my border collie, Scout, needed emergency surgery after debris from a twister lacerated his paw—and our “comprehensive” plan had a gaping exclusion for “acts of nature.” Don’t let paperwork bury your peace of mind. This guide breaks down exactly how to secure real emergency vet tornado coverage plan in policies that actually pay out when skies turn green.
Table of Contents
- Why Tornado Coverage Matters for Pets
- Your Step-by-Step Guide to Securing Coverage
- Best Practices for Maximum Protection
- Real-World Examples That Prove It Works
- Frequently Asked Questions
Key Takeaways
- Standard pet insurance often excludes tornado-related injuries—always verify “natural disaster” clauses.
- Only 38% of U.S. pet owners have emergency funds covering over $1,000 in vet bills (ASPCA).
- Adding emergency boarding or evacuation transport can prevent coverage gaps.
- File claims within 48 hours post-disaster to avoid denials.
Why Tornado Coverage Matters for Pets
Tornadoes strike fast and leave chaos: flying glass, collapsed fences, contaminated water—all prime hazards for panicked pets. A 2023 study by the American Veterinary Medical Association found that emergency vet visits spike 22% in tornado-prone counties during storm season. Yet most base-level pet insurance plans exclude “environmental catastrophes,” leaving owners drowning in $2,000+ bills for wound treatment or toxin ingestion.
My mistake? Assuming “accident coverage” meant tornados. It didn’t. Scout’s $1,800 ER visit was denied because the policy fine print excluded “weather-induced trauma.” That pain taught me: if your plan doesn’t explicitly include emergency vet tornado coverage plan in its covered perils list, it’s worthless when sirens wail.
Your Step-by-Step Guide to Securing Coverage
1. Audit Your Current Policy
Grab your policy PDF and Ctrl+F for “tornado,” “severe weather,” or “natural disaster.” If absent, assume you’re uncovered. Call your insurer and ask: “Does this cover emergency vet visits caused directly or indirectly by a tornado?” Get the answer in writing.
2. Compare Specialized Add-Ons
Brands like Trupanion and Nationwide offer “Catastrophe Riders” ($8–$15/month extra) that include tornado-related ER care, evacuation transport, and even temporary boarding. Never skip this—it’s cheaper than one ER copay.
3. Document Everything Pre-Storm
Take dated photos of your pet’s health pre-tornado season. Insurers may deny claims alleging pre-existing conditions aggravated by stress. Also, save NOAA storm alerts as proof of event timing (National Weather Service archives are admissible).
Best Practices for Maximum Protection
- Bundle with Home Insurance: Some providers (like State Farm) discount pet riders when bundled with homeowner policies covering storm damage.
- Avoid the “Annual Limit” Trap: Choose plans with per-incident—not annual—caps. One tornado injury shouldn’t max out your whole year’s coverage.
- Never Rely on Crowdfunding: GoFundMe campaigns fail 61% of the time for vet bills (Journal of Veterinary Emergency Medicine). Insurance pays faster and reliably.
And here’s a terrible tip I’ve heard far too often: “Just use human disaster relief funds for pets.” Nope. FEMA explicitly states pet expenses aren’t covered under individual assistance (FEMA.gov). Don’t bank on it.
Real-World Examples That Prove It Works
In 2022, Oklahoma resident Maria R. activated her Nationwide Catastrophe Rider when her cat inhaled smoke from a tornado-sparked fire. The plan covered $3,200 in oxygen therapy and diagnostics—because her policy included “secondary environmental hazards.” Contrast that with Ben T. in Alabama, whose basic ASPCA plan denied his dog’s broken leg claim post-tornado, citing “excluded peril.” The difference? Explicit emergency vet tornado coverage plan in language. Maria’s rider cost $12/month. Ben paid $2,900 out-of-pocket.
Data confirms it: Policies with named disaster coverage see 92% claim approval rates versus 47% for standard plans (North American Pet Health Insurance Association, 2023).
Frequently Asked Questions
Does pet insurance cover tornado evacuation costs?
Only if you’ve added an emergency transport rider. Base plans rarely include travel or boarding.
Can I get coverage right before storm season?
Yes, but expect a 14-day waiting period. Enroll early—don’t wait for the first thunderclap.
Are pre-existing conditions excluded even during tornadoes?
Always. Chronic issues (like arthritis) aggravated by storm stress won’t be covered. But new injuries (lacerations, fractures) will.
How fast must I file a tornado-related claim?
Within 48 hours. Delays raise red flags about claim legitimacy.
Is emergency vet tornado coverage plan in all states?
Availability varies by insurer, not state law. Verify with providers directly—especially in high-risk zones like Tornado Alley.
Securing true emergency vet tornado coverage plan in policies isn’t just smart—it’s survival. When winds howl and kennels crack, you need more than hope; you need bulletproof paperwork. Ready to shield your furry family? Contact us for personalized comparisons. We’ve helped hundreds navigate insurer fine print—learn more about our mission on the About Us page, and rest easy knowing your data stays private per our Privacy Policy.
Because when the sky falls, your pet’s safety net shouldn’t tear.