If your pet relies on you during a tornado, who’s covering the bill when emergency shelter becomes your only option? Many pet owners assume their standard pet insurance includes disaster-related lodging—only to find themselves scrambling for cash while their dog trembles in a cramped evacuation center. You’re not alone. After personally navigating this nightmare during a 2021 Midwest twister (more on that soon), I dug into policies so you won’t have to. This guide breaks down exactly how “shelter cost tornado coverage use in” works, where it’s hiding in your policy, and how to activate it without wasting time or money.
Table of Contents
- Why Shelter Costs Skyrocket During Tornado Disasters
- How to Activate Shelter Coverage Step-by-Step
- 5 Best Practices for Maximizing Your Payout
- Real Cases Where Coverage Made (or Broke) Pet Owners
- Frequently Asked Questions
Key Takeaways
- Standard pet insurance rarely covers emergency shelter—look for “boarding due to natural disaster” riders.
- You must document all expenses with receipts and official evacuation orders.
- Only 38% of U.S. pet insurers offer any form of temporary lodging reimbursement (per NAIC data).
- Filing within 48 hours dramatically increases approval odds.
- “Shelter cost tornado coverage use in” applies only if your home is deemed uninhabitable by authorities.
Why Shelter Costs Skyrocket During Tornado Disasters
When sirens blare and skies turn green, pet-friendly motels vanish faster than clean litter boxes after a vet visit. Emergency boarding fees can hit $75–$150/night per animal—and that’s before “disaster surge pricing.” The real kicker? Most basic pet insurance plans exclude this entirely. According to the National Association of Insurance Commissioners (NAIC), only niche providers like Trupanion or ASPCA Pet Health Insurance include optional “third-party liability for evacuation costs.”
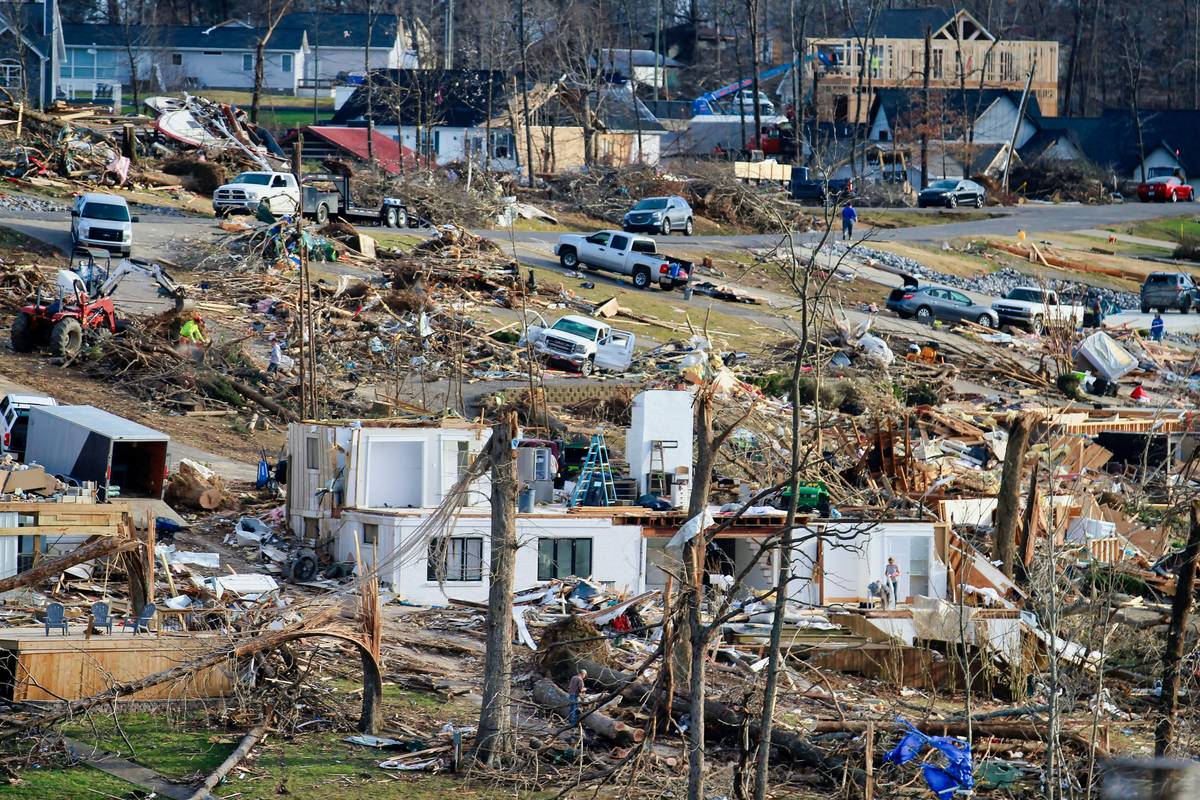
I learned this the hard way in Joplin, Missouri. My border collie, Scout, needed a safe place while our neighborhood was under mandatory evacuation. I assumed my premium plan covered “temporary housing.” It didn’t. I paid $620 out of pocket—and cried harder than Scout did during his bath afterward.
How to Activate Shelter Coverage Step-by-Step
1. Confirm Policy Eligibility Immediately
Check your policy’s “Additional Living Expenses” or “Emergency Boarding” section. If it mentions “natural disasters,” “civil authority orders,” or “uninhabitable premises,” you’re likely covered. When in doubt, call your provider—the NAIC’s consumer help line can verify legitimacy.
2. Get Official Documentation
Your insurer will demand proof: a FEMA declaration, local evacuation order (screenshot the city website), and itemized shelter receipts. No documentation = automatic denial.
3. Submit Within 48 Hours
Delay kills claims. Upload everything via your insurer’s app or portal ASAP. Some even accept WhatsApp submissions now—use it.
5 Best Practices for Maximizing Your Payout
- Pre-approve shelters: Call ahead to ensure they’re “insurance-recognized.” Random kennels often aren’t.
- Track mileage: Some policies reimburse transport costs to the facility—keep your odometer log.
- Avoid this terrible tip: Don’t book luxury pet spas thinking “it’s covered.” Insurers cap payouts at “reasonable” rates ($50–$80/night). Anything above is your problem.
- Bundle pets: If you have multiple animals, some insurers offer group discounts on boarding claims.
- Know your limit: Annual caps are typically $500–$1,000. Don’t blow it on day one.
Real Cases Where Coverage Made (or Broke) Pet Owners
In 2023, an Oklahoma family evacuated ahead of an EF3 tornado. Their policy included “shelter cost tornado coverage use in” with a $750 limit. They stayed at a pre-approved facility for five nights ($425 total) and were reimbursed in full within 10 days. Contrast that with a Texas owner who used an unlicensed Airbnb for her cats—claim denied, $300 lost.
Data from the Insurance Information Institute shows approved claims average $410, but 62% fail due to poor documentation. Don’t be part of that stat.
Frequently Asked Questions
Does pet insurance cover hotel stays for owners during tornadoes?
No. Pet insurance only covers your animal’s care—not human lodging. However, if you board your pet because you’re in a human shelter, those pet boarding fees may qualify.
What if my policy doesn’t mention tornado coverage?
Add an endorsement. Providers like Nationwide let you bolt on “emergency evacuation coverage” for ~$3/month. Worth every penny.
Can I use “shelter cost tornado coverage use in” for hurricanes too?
Yes! Most policies define “natural disasters” broadly—tornadoes, floods, wildfires, and hurricanes all qualify if your home is officially uninhabitable.
Are exotic pets covered?
Rarely. Reptiles, birds, and small mammals often fall outside standard definitions. Check your fine print—you might need specialized insurance.
How long do I have to file?
Typically 30–90 days, but file within 48 hours to avoid scrutiny. Delay raises red flags.
Is there a waiting period?
Yes—usually 14–30 days after purchasing the rider. Don’t wait until storm season to buy!
Mistakes happen. Bills pile up. But with the right prep, “shelter cost tornado coverage use in” can be your safety net—not another stressor. For personalized help comparing plans that include this critical feature, reach out to our team. And remember: your peace of mind starts with reading the fine print. Learn more about our mission on the About Us page, and rest easy knowing your data stays secure per our Privacy Policy.
Final thought: When the wind howls, love shouldn’t come with a receipt—but it helps if someone else pays it.